Giulia Bins

Work / will bank

Offering insurance without getting in the way

Nobody opens a bank app to buy insurance. So I took the offer to the moments where protection makes sense: right after a Pix, after paying the card bill, after saving money. Then we measured every spot and kept only what worked.

Role
Staff Product Designer
When
2025
Product
Insurance offers across the will bank app
Focus
Interaction design, experimentation
  • 66%of card insurance with Disney+ sales came from the offer right after a Pix
  • +222%revenue after a Pix when the offer became card insurance with Disney+
  • 240%better conversion on the Home minicard with a prize draw than with a carnival card theft argument
  • 11places in the app, each one measured, the weak ones switched off

Context

At will bank I led design for commissioned products: insurance, mobile top-up and capitalization. Insurance isn't top of mind for anyone, and even less for our customers, people in classes C and D.

Our research showed that people decide to buy protection in moments of transition and new risk. Waiting for them to find the insurance hub wasn't going to work.

Offer protection right after the moment it makes sense, never before the task is done.

What I designed

I designed contextual offers: small insurance offers that show up where the customer already is, and talk about what they just did. Moved money with Pix? Protect your card. Paid the bill? Your card can be protected too.

A few rules kept them out of the way:

  • The offer comes after the task, on the success screen, never as a step in the middle of it.
  • One line, one tap. It never covers the screen or blocks the main button.
  • The words connect to the moment, not to "insurance" in general.
  • Each spot ran on its own, with its own numbers, so we could switch off the ones that didn't work.
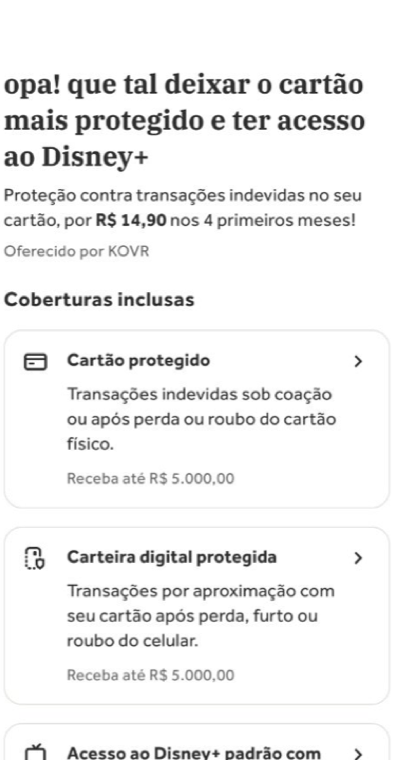
After a PixOffer screen after a Pix: 'how about keeping your card more protected and getting Disney+', with the included coverages.The offer that sold mostRight after money moved
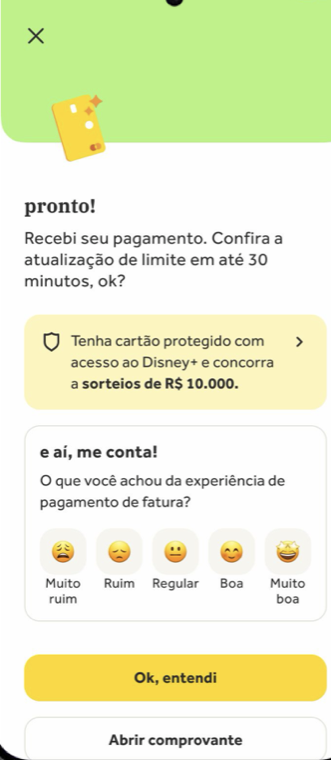
After paying the billSuccess screen after paying the card bill, with a one-line offer: protected card with Disney+ and R$10,000 prize draws.On the success screenOne line, after the task
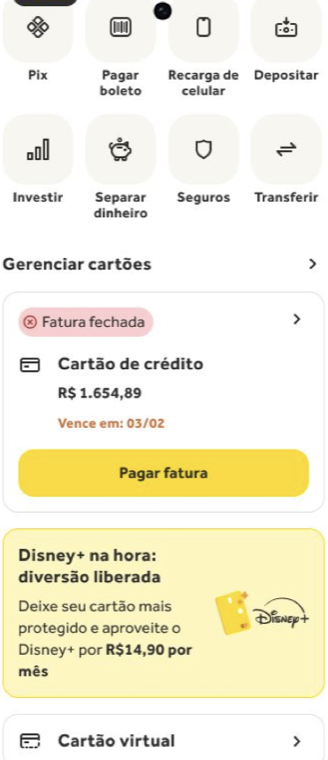
HomeApp Home with a card under the credit card bill: 'Disney+ right now, fun unlocked', protect your card and get Disney+ for R$14.90 a month.Under manage cardsNext to the card bill
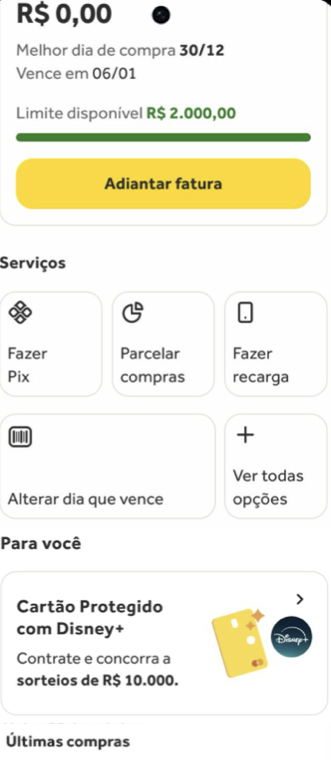
Credit homeCredit home with a 'For you' card: protected card with Disney+, sign up and enter R$10,000 prize draws.In "For you"Lots of views, few sales
Four of the offer points I designed for card insurance with Disney+. The app was in Portuguese.

What we tested

Every offer point was an experiment. A few that shaped the rest:

  • Which product on the Home minicard. Card insurance got 28% more sign-ups than account insurance, so card insurance became the main offer.
  • Which argument. The test ran right at carnival, when cards and phones get stolen a lot in the crowds. So one version said: protect your card for carnival. The other offered a monthly R$10,000 prize draw. The prize draw converted 240% better. The same pull showed up again when people built their own insurance.
  • Which offer after a Pix. Swapping the old offers for card insurance with Disney+ lifted conversion by 49% after a regular Pix, and revenue by 222%. After a Pix on credit, conversion dropped 46%, so that one went back to review.

Where the Disney+ offer sold

Policies sold by offer point, with how many times each offer was seen

  • After a Pix1.4M views
    5,782
  • Home, under manage cards3.5M views
    1,717
  • Credit home2.5M views
    270
  • Account home2.1M views
    244
  • After paying the bill1.7M views
    88
  • After paying a boleto226K views
    28
  • Virtual card details176K views
    5
  • Physical card details86K views
    2
Redrawn from the offer results, late 2025. Each offer ran for a different period.

What the numbers said

  • Context beat traffic. After a Pix had fewer views than the Home, and sold more than three times as much.
  • Busy screens didn't sell. Credit home and account home had millions of views and converted almost nothing. They became candidates for a propensity model, showing the offer only to people more likely to want it.
  • Some spots were switched off. Card details sold almost nothing, so we turned those offers off.
  • Selling isn't the whole story. Offers after paying the bill sold less but kept customers longer. After a Pix sold the most, but had more cancellations. We started checking whether an offer that proactive was leading to sign-ups people didn't really mean.

What came next

The research had shown that the word "insurance" itself pushed our customers away. The next test was to call it protection instead, starting with the offer in manage cards. More offer points were lined up for pockets and CDB.
The best place to offer insurance wasn't the busiest screen. It was the moment right after someone moved their money.

Every offer point had its own number, so the team could keep, change or switch off each one based on data.